7 Roof Leak Repair Financing Options That Actually Work
Last Updated: November 18, 2026
Quick Summary
Roof leak repair financing options include personal loans, home equity loans and HELOCs, cash-out refinancing, contractor payment plans, credit cards, and government programs. Personal loans fund in days with no collateral, while home equity products cost less but take weeks to close. Get a written project estimate before applying so you borrow only what the repair requires.
- Personal loans are unsecured and fund in days, but carry higher APRs and smaller amounts.
- Home equity loans and HELOCs offer lower rates but put your house on the line.
- Prequalify with two or three lenders before applying to avoid multiple hard credit pulls.
- No-credit-check offers often carry higher APRs, larger down payments, or prepayment penalties.
- Stabilize an active leak first, then compare financing while the tarp is up.
Table of Contents
- Compare Roof Leak Repair Financing Options at a Glance
- Personal Loans and Home Equity: Secured vs. Unsecured Roof Financing
- Roof Financing With Bad Credit: What Lenders Actually Look At
- Roof Financing No Credit Check: What's Real and What to Avoid
- Roofing Companies With Payment Plans Near Me: How to Vet Local Offers
- Government Loans for Roof Replacement: What Texas Homeowners Qualify For
- Emergency Leak Triage: When to Finance a Repair vs. a Full Replacement
- Get a Free Inspection and Lock In Your Financing Plan
- Frequently Asked Questions
Compare Roof Leak Repair Financing Options at a Glance
A roof leak rarely waits for a convenient moment. When water is staining your ceiling in Katy, TX, the first question is how to pay for the fix without draining your savings.
Here's the short version: personal loans fund fast with no collateral, home equity loans cost less but take longer to close, contractor financing bundles the work and the payment, and credit cards only make sense for small repairs you can clear quickly.
The table below summarizes what each option is best at.
| Financing Option | Secured? | Typical Speed | Best For |
|---|---|---|---|
| Personal loan | Unsecured | Days | Fast funding, no home equity |
| Home equity loan | Secured | Weeks | Lower rates, larger projects |
| HELOC | Secured | Weeks | Flexible draws, phased repairs |
| Cash-out refinance | Secured | Weeks to months | Replacing a mortgage rate too |
| Contractor financing | Varies | Same day | Bundling work and payment |
| Credit card | Unsecured | Immediate | Small repairs, short payoff |
| Government programs | Varies | Varies | Qualifying households only |
NerdWallet's roof financing comparison lays out the same core categories: personal loans, home equity borrowing, cash-out refinancing, and roofing-company financing. Before you apply anywhere, get a written project estimate. You cannot judge a loan amount without knowing the repair cost, and our Katy and Houston roof repair pricing tiers give you a real starting point.
Personal Loans and Home Equity: Secured vs. Unsecured Roof Financing
The secured versus unsecured split decides more than your rate. It decides what you risk.
An unsecured loan is a personal loan with no collateral attached. The lender approves you on credit history and income alone, funds land in days, and your house is never on the line. The trade-off is a higher annual percentage rate and a smaller loan amount.
A secured loan ties the debt to your home equity. Home equity loans and HELOCs usually carry lower interest rates and longer loan terms, but the house backs the debt, and closing costs and origination fees often apply.
A common mistake is assuming the lower rate always wins. If you can repay a small repair in under a year, an unsecured loan with a slightly higher rate can cost less overall than a secured loan with fees.
Roof Financing With Bad Credit: What Lenders Actually Look At
Roof financing with bad credit is possible, but the terms change. Lenders weigh your credit score alongside income stability, existing debt, and how much equity you hold. A weak score pushes you toward higher APRs or a cosigner requirement.
Here is what actually moves an approval:
- Payment history carries the most weight, so recent on-time payments help
- Debt-to-income ratio matters more than a single score for many lenders
- Home equity can offset a lower score on secured products
- Prequalification lets you see offers without a hard credit pull
Prequalify with two or three lenders before applying. Each formal application can ding your score slightly, so compare offers first, then apply once with the best fit. Watch out: a lender that promises approval with no credit review at all is usually charging for that convenience through fees or a much higher rate.
Roof Financing No Credit Check: What's Real and What to Avoid
Roof financing with no credit check exists, but the category needs a hard look. Contractor in-house payment plans and some home improvement lenders skip the full credit pull because they price the risk into the terms instead.
What most guides miss is the cost of that convenience. No-credit-check offers often carry higher APRs, larger down payments, or prepayment penalties. Some are legitimate. Others are predatory.
Use this checklist before signing anything:
- Is the APR disclosed in writing, including fees?
- Is there a prepayment penalty for paying early?
- Does the lender hold a license to lend in Texas?
- Are the monthly payments something you can cover in a slow month?
- Is there a lien placed on your home, and can you live with it?
If a lender dodges any of those questions, walk away. A denied application costs you nothing. A bad contract costs you for years.
Roofing Companies With Payment Plans Near Me: How to Vet Local Offers
Searching for roofing companies with payment plans near me returns plenty of ads. The vetting matters more than the search.
Ask every contractor three things: who actually holds the loan, what the full repayment looks like, and what happens if the work is delayed. A payment plan through a contractor is only as good as the company standing behind it. If the roofer disappears, you still owe the lender.
For homeowners who want the work and the financing conversation in one place, our local roof repair page with same-day estimates and $0-down financing shows what a transparent offer looks like. Here's what separates a solid local offer from a thin one:
- The contractor provides a written project estimate before any financing talk
- Financing terms are disclosed in writing, not quoted verbally
- The company can explain how insurance claims interact with the payment plan
- Reviews are verifiable and recent
Credible's guide to financing roof repairs also lists contractor financing alongside traditional loans, which is a useful reminder that the contractor route is one option among several, not the default.
Government Loans for Roof Replacement: What Texas Homeowners Qualify For
Government-backed roof financing in Texas is narrower than most search results suggest. There is no broad federal loan program that simply pays for a roof replacement. What exists are targeted programs with specific eligibility gates, and understanding those gates is the difference between a useful application and a wasted credit pull.
The main federal options homeowners may encounter are:
- FHA Title I Property Improvement Loans. These are offered through approved private lenders and insured by the Federal Housing Administration (Title I Insured Programs). They can finance roof repair or replacement as a home improvement, with loan amounts that vary by lender and property type. The catch is that you apply through a participating lender, not the FHA directly, and the lender sets the rate and terms within FHA guidelines. Not every roofer or lender participates, so ask upfront.
- USDA Section 504 Home Repair Loans and Grants. Available only for eligible rural properties and low-income households. The program is designed for very-low-income owners age 62 and older for grants, and low-income owners for loans. If your Katy-area property is in an eligible rural zone, this can be a low-cost option, but the income and location screens are strict.
- Local weatherization and disaster assistance. These are event-specific. A storm-damaged roof in a federally declared disaster area may open FEMA individual assistance or Small Business Administration disaster loans, but a worn-out roof from age never qualifies. SBA disaster loans are available to homeowners in declared disaster areas and can cover roof repair, but they are not a routine maintenance financing tool.
A common pattern is for homeowners to confuse PACE (Property Assessed Clean Energy) financing with a government grant. PACE is a private financing arrangement repaid through a property tax assessment, and availability varies by county and program administrator.
Eligibility for any of these programs depends on your location, income, and the nature of the damage. Before chasing a government loan, check whether insurance already covers the replacement. Our guide to how insurance covers roof replacement in Texas explains the claims path, and for many homeowners that path settles the cost question entirely.
Watch out: Some contractors advertise "government-backed financing" when they mean a private loan with a government guarantee attached to the lender, not a direct government program. Ask who actually holds the note and whether the loan is FHA-insured, USDA-direct, or simply a private loan with a marketing label.
Emergency Leak Triage: When to Finance a Repair vs. a Full Replacement
Active leaks force a decision fast, and financing a repair you didn't need is as costly as under-financing a replacement.
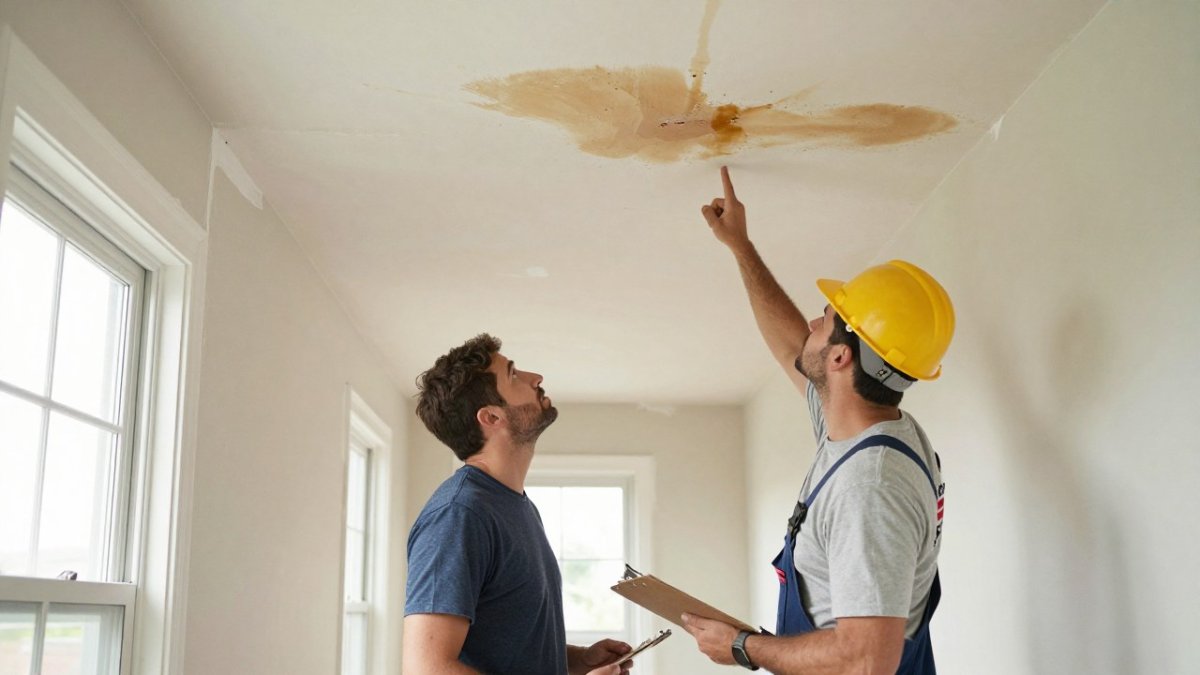
Temporary versus permanent work changes your financing math. A temporary repair like a tarp, sealant, or flashing patch might cost a few hundred dollars and buy you weeks to compare financing.
Triage comes down to three questions. Is the leak isolated to one area with intact surrounding shingles? Is the decking underneath sound? Is the roof past its expected service life? If triage points to a full replacement, our Katy roof replacement service with $0-down financing covers what that project involves.
Coordinate insurance and financing before you sign a loan. If you plan to file a claim, get the contractor's written estimate and the adjuster's scope before you commit to a loan amount.
Do not let financing comparison delay emergency stabilization. The worst outcome is a tarp that never gets placed because you were comparing APRs. Stabilize first, then compare.
Watch out: A contractor who pressures you to sign a financing agreement before providing a written scope and before you have compared at least one other offer is rushing a decision that should take a day, not an hour.
Get a Free Inspection and Lock In Your Financing Plan
The financing decision starts with an accurate diagnosis, not a lender's website. You need a written scope of work before you can choose a loan amount, a term, or a repayment schedule that fits.
That is where we come in. Roof Repair Company provides free storm and hail damage inspections with a written summary of findings you can use for an insurance claim.
Get your inspection first, then finance the number you actually need. Book a roof inspection with written findings and photo documentation and ask about available appointment times.
Water damage compounds by the day, and a financing decision made without a real diagnosis usually costs more than the repair itself. Roof Repair Company handles the inspection, the written findings, the insurance coordination, and the pricing transparency so you can choose a payment plan with confidence.
Frequently Asked Questions
Can I finance a roof leak repair with bad credit?
Yes, though your options narrow. Home equity loans and HELOCs typically require stronger credit and sufficient equity. Personal loans for roof leak repair are available to borrowers with fair credit, but expect higher APRs than secured options. Contractor financing may be the most accessible route because approval is often based on the project rather than your score alone. Get a written estimate first, then compare at least two offers before signing.
Are there roof repair financing options with no credit check?
Some contractors advertise no credit check payment plans, but read the terms closely. These arrangements often carry higher fees, shorter repayment windows, or require a larger down payment. Legitimate no credit check options exist through certain contractor financing programs, but they are not the same as a standard personal loan. Ask for the full payment schedule in writing, confirm whether interest is deferred or compounding, and never agree to a plan that lacks a written contract.
Will homeowners insurance pay for a roof leak repair?
It depends on the cause. Sudden damage from a storm, hail, or a fallen limb is typically covered. Damage from age, poor maintenance, or a long-standing slow leak is usually excluded. Document the damage with photos before any temporary repairs, file the claim promptly, and request a written inspection summary from your roofer that you can submit to your adjuster. Having a contractor present at the adjuster meeting can help clarify scope and prevent a low initial offer.
Is a personal loan or contractor financing better for roof leak repair?
Personal loans often offer fixed rates and predictable monthly payments. Contractor financing may be faster to arrange and sometimes includes promotional rates, but terms vary widely by company. Compare the total cost of borrowing, not just the monthly payment. If your credit is strong and the repair is under a few thousand dollars, a personal loan is often simpler. For larger projects, a home equity line of credit may offer lower rates.