How to Handle an Insurance Claim Denial for Your Roof
Table of Contents
- Why Roof Insurance Claims Get Denied
- Step 1: Read Your Insurance Claim Denial Letter Carefully
- Step 2: Gather Your Roof Damage Insurance Claim Documentation
- Step 3: Write Your Insurance Claim Appeal Letter Template
- Step 4: Get an Independent Roof Inspection
- How Long Does an Insurance Claim Appeal Take?
- When to Escalate to the Texas Department of Insurance
- Frequently Asked Questions
Last Updated: October 21, 2026
Why Roof Insurance Claims Get Denied
An insurance claim denial is a written decision by your insurer to refuse payment for part or all of a roof damage claim. It is not the final word. Most denials can be challenged, and many homeowners who appeal successfully recover part or all of what they were owed.
The pattern is predictable. Here is what usually went wrong.
The Most Common Denial Reasons
Most roof denials come down to a short list of causes:
- Wear and tear - the insurer says the damage built up over years, not from one storm
- Missed filing deadline - the claim arrived after the policy's notice window closed
- Insufficient documentation - photos were blurry, undated, or missing
- No proof of storm event - no weather report tied to the damage date
- Deductible confusion - the repair cost fell below what you owe out of pocket
- Adjuster disagreement - the adjuster found less damage than your contractor did
Each reason needs a different response. A deadline problem is a paperwork fight. A wear-and-tear ruling is a technical fight.
Step 1: Read Your Insurance Claim Denial Letter Carefully
Your insurance claim denial letter is a legal document, not a form letter. It must state the specific reason for the denial and cite the policy language the insurer relied on.
Read it twice. First for the reason. Second for the deadline.
Look for these items:
- The exact policy section quoted
- The date the insurer received your claim
- Any appeal window stated in days or months
- The name and contact of the person handling your file
- Whether the denial covers the whole claim or just part of it
Partial denials are common and easier to overturn than full denials. If the letter says the roof is covered but the price is too high, that is a valuation dispute, not a coverage dispute. Those often resolve with a second inspection.
Write down the appeal deadline on your calendar today. Missing it is the one mistake no appeal can fix.
Step 2: Gather Your Roof Damage Insurance Claim Documentation
Strong roof damage insurance claim documentation wins appeals. Weak documentation loses them, no matter how obvious the damage looks in person.
Build a file with these items:
Documentation Checklist
- The full denial letter, scanned
- Your original claim number and policy number
- Your complete policy, including the declarations page
- Dated photos of the damage, taken from ground and roof level
- Close-ups of damaged shingles, granules, or metal panels
- A weather report for the storm date from a national weather source
- Receipts for any emergency repairs or tarping
- Notes from any contractor who inspected the roof
- Your written summary of when you first noticed the damage
- Copies of every email and letter exchanged with the insurer
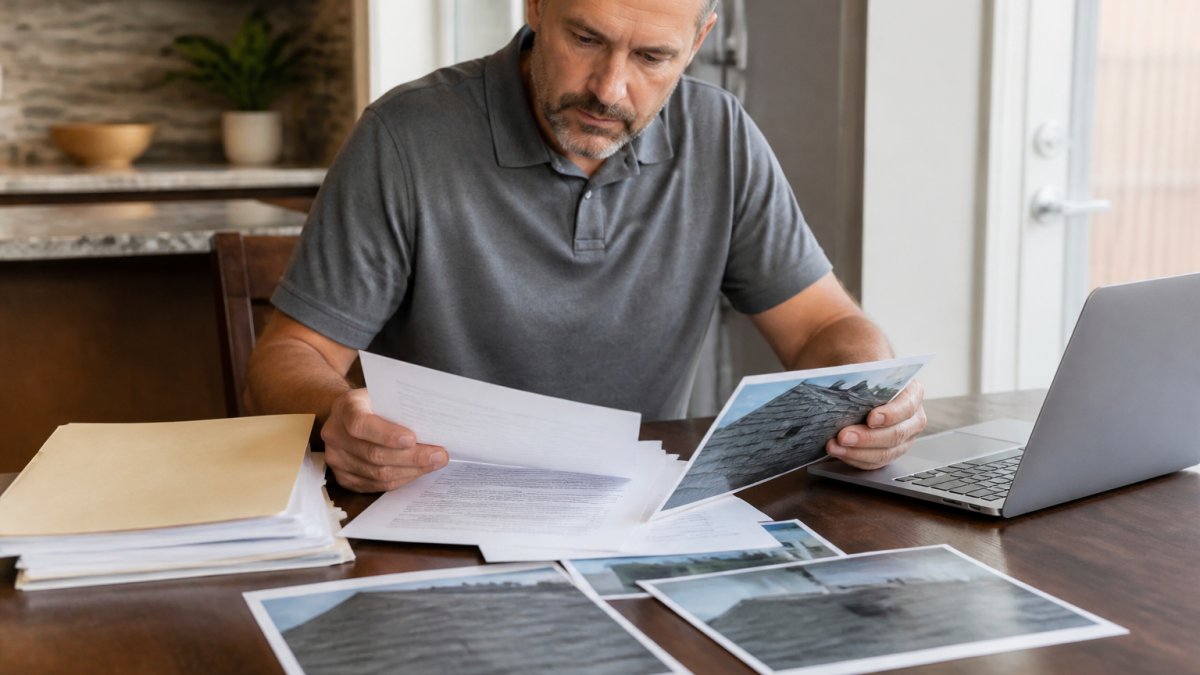
Keep everything in one folder, digital and paper. Send copies, never originals.
The weather report matters more than people expect. A dated storm record from a national source like the National Weather Service turns "wear and tear" into "hail event on a specific day."
Step 3: Write Your Insurance Claim Appeal Letter Template
An insurance claim appeal letter template gives you the structure insurers expect. Keep it short, factual, and tied to the policy.
Here is the format we recommend:
[Your Name] [Your Address] [Date]
[Insurer Name] Claims Department [Insurer Address]
Re: Appeal of Claim Denial - Policy [Number], Claim [Number]
Dear Claims Review Team,
I am appealing the denial dated [date] for roof damage at [property address]. I disagree with the decision for the reasons below.
Reason for denial as stated: [quote the letter]
Why this is incorrect: [one paragraph, with facts]
Supporting documents enclosed:
- [Document name]
- [Document name]
- [Document name]
Please reopen this claim and arrange a reinspection. I can be reached at [phone] and [email].
Sincerely, [Signature] [Printed name]
Keep the tone neutral. Do not argue about fairness or accuse anyone of bad faith. Stick to dates, documents, and policy language. Send it by certified mail and keep the receipt.
Step 4: Get an Independent Roof Inspection
An independent roof inspection gives you a second, technical opinion that the insurer's adjuster did not provide. It is the strongest single piece of evidence in most appeals.
A licensed roofing contractor can document things an adjuster may miss:
- Hail bruising on shingles that is invisible from the ground
- Cracked pipe boots and damaged flashing
- Granule loss patterns that show impact rather than age
- Storm direction and how it matches the damage pattern
- A written summary of findings you can attach to your appeal
Ask for a written report with photos, not a verbal opinion. Insurers weigh written reports far more heavily.
We provide free storm and hail damage inspections, attend on-site adjuster meetings, and give you a written summary of findings built for claims. Our satellite-based roof measurement gives you an accurate square count before anyone sets foot on the roof, so you are not guessing at scope.
If you are searching for roof claim help near me in the Katy area, book a free inspection before you mail the appeal. A technical report in hand changes how insurers read your letter.
How Long Does an Insurance Claim Appeal Take?
Most appeals take 30 to 60 days for a written decision. Complex cases with reinspections can run longer.
Timelines vary by insurer and by whether a second adjuster visit is required. Here is how the process usually flows:
| Stage | Typical Time | What Happens |
|---|---|---|
| Insurer receives appeal | 1-2 weeks | File logged and assigned |
| Internal review | 2-4 weeks | Reviewer reads documents |
| Reinspection | 1-3 weeks | Adjuster visits the roof |
| Final decision | 1-2 weeks | Written approval or denial |
Add a few weeks if you request an appraisal or file a complaint with a regulator. Keep copies of everything and follow up in writing every two weeks.
The single most important insight on timing: your appeal window is set by your policy and state rules, not by the insurer's convenience. Note the deadline the day the denial arrives, and mail your appeal well before it.
When to Escalate to the Texas Department of Insurance
Escalate to the Texas Department of Insurance (TDI) when your appeal is denied again, when the insurer misses its own response deadline, or when you believe the company handled the claim unfairly.
TDI regulates insurers in Texas. It does not force a company to pay a claim, but it does investigate complaints and track patterns. A formal complaint often gets your file a second look from a different team.
Before you file, confirm the current complaint process and any deadlines on the Texas Department of Insurance website. Rules and forms change, so check the official page rather than relying on older advice.
You can also ask about the appraisal clause in your policy. Appraisal is a dispute process where each side hires an independent appraiser, and a neutral umpire settles the difference. Many policies include it. It is often faster than a lawsuit and cheaper than an attorney.
Escalation is a last step, not a first one. Exhaust the appeal and reinspection route first. Insurers respond better to a well-documented file than to a complaint filed too early.
A denied roof claim feels like a dead end, but it is usually a paperwork problem you can fix. The homeowners who win appeals are the ones who read the letter closely, gather dated evidence, and get a written inspection report before they respond.
If your roof claim in Katy, TX was denied, we can help you build that file. We offer free storm and hail damage inspections, on-site adjuster meetings, and a written summary of findings for your claim. Our GAF Master Elite certification and 1,122 customer reviews back the work, and our satellite measurement gives you accurate scope from day one. Get started with a free inspection, then appeal with evidence instead of guesswork.
Frequently Asked Questions
What should I do first if my roof insurance claim is denied?
Start by reading the denial letter line by line. It states the specific reason for the denial, whether that is wear and tear, a deductible issue, or a missed filing deadline. Note the appeal deadline listed in the letter and the name of the adjuster who handled your file. Then request a copy of the adjuster's report and any photos they took. That report is the foundation of your appeal, because it shows exactly what the insurer says it saw on your roof.
How long do I have to appeal an insurance claim denial in Texas?
The deadline depends on your policy language, so check the denial letter and your policy documents for the exact window. Many Texas homeowners policies give you a set period to request a re-inspection or submit a formal appeal, and missing it can close the file. If you are unsure, call your adjuster and ask for the deadline in writing. Document that call. Filing your appeal early gives you room to gather inspection reports and photos before the clock runs out.
Should I get an independent roof inspection after a claim denial?
Yes, in most cases. An independent inspection from a licensed roofing contractor gives you a second opinion backed by photos and measurements that may contradict the adjuster's findings. Ask for a written summary of findings you can attach to your appeal. A contractor who handles insurance claims regularly can also point out damage the original adjuster missed, such as hail bruising on shingles or lifted flashing that only shows up close.
Can I reopen a denied roof insurance claim?
Often you can, but the process varies by insurer. Some companies allow a formal appeal or reconsideration request, while others require you to file a new claim with new evidence, such as a contractor's inspection report or updated photos. Call your insurer and ask what the reconsideration process looks like and what documentation they need. Keep copies of everything you submit, and follow up in writing so you have a record of each step.